
Federal Reserve's Long-Term Interest Rate Path Below 4.0% by 2027 Spurs Economic Debate
The trajectory of the Federal Reserve's benchmark interest rate over the coming years has emerged as a central point of contention among economists, policymakers, and investors. A key focus is whether the federal funds rate will ultimately settle below the 4.0% threshold by the close of 2027, a scenario that holds profound implications for the U.S. and global economies. This discussion is not merely academic; it shapes market expectations, influences corporate investment decisions, and impacts the financial well-being of households.
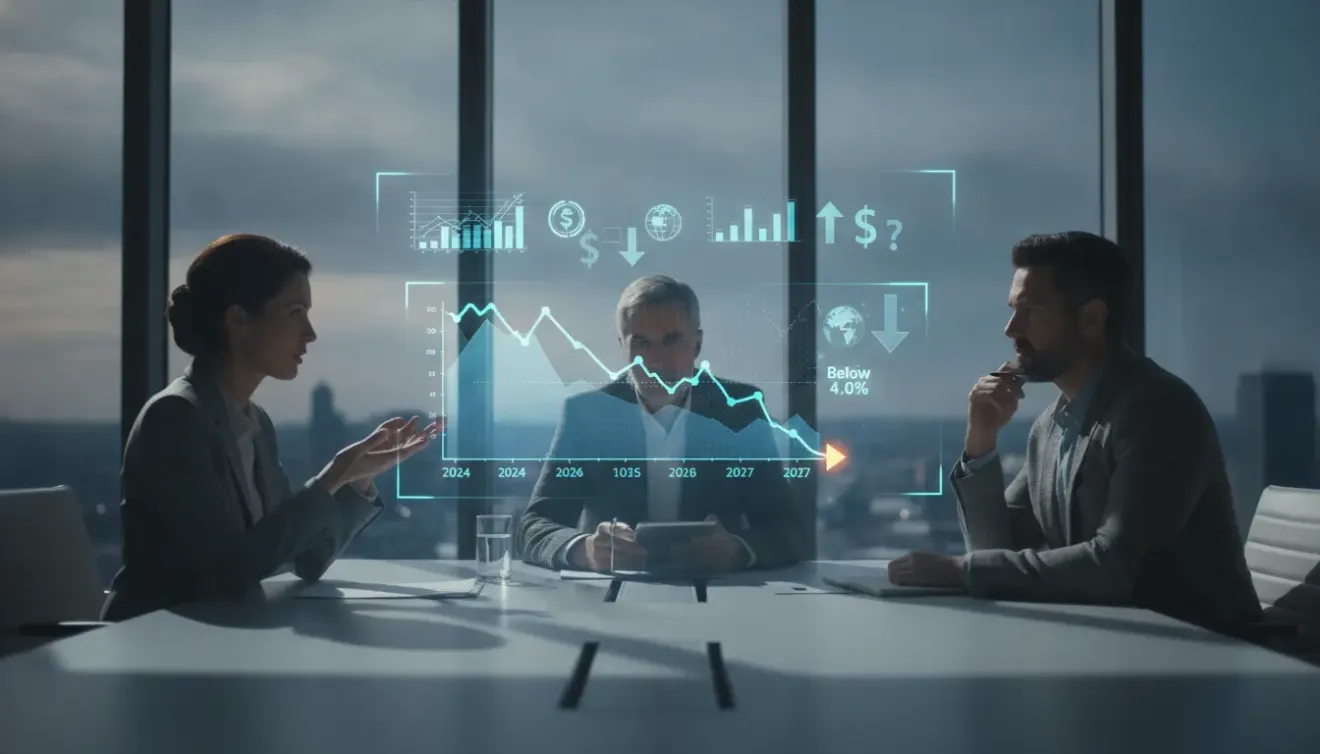
Following an aggressive hiking cycle initiated in early 2022 to combat surging inflation, the Federal Reserve has steered the federal funds rate to a range not seen in over two decades. The prevailing sentiment through much of 2023 was one of “higher for longer,” as persistent price pressures and a resilient labor market seemed to warrant a restrictive stance. However, as inflation shows signs of moderation, albeit unevenly, attention is increasingly turning to the long-term equilibrium, often referred to as the “neutral rate” — the theoretical rate at which monetary policy is neither stimulative nor restrictive. Policymakers’ projections, often visualized in their quarterly “dot plots,” reflect a wide divergence of views on where this neutral rate, and thus the policy rate, will ultimately land, especially over a multi-year horizon.
At the core of this debate is the unpredictable path of inflation. While the Consumer Price Index (CPI) and Personal Consumption Expenditures (PCE) index have decelerated from their peaks, reaching the Fed’s symmetrical 2% target on a sustained basis remains a challenge. Should inflation prove more entrenched or experience an unexpected resurgence, perhaps driven by supply-side shocks or robust demand, the central bank would likely maintain higher rates for longer, pushing the prospect of a sub-4.0% rate further into the future. Conversely, a clear and convincing return to the inflation target could provide ample room for the Fed to ease policy, aligning rates closer to or even below 4.0% to avoid stifling economic activity.
Economic growth and the state of the labor market serve as equally critical variables. A strong, non-inflationary expansion, characterized by healthy productivity gains and moderate wage growth, could allow for a gradual reduction in rates without triggering price pressures. However, if the economy experiences a significant slowdown, or even a recession, the Fed would almost certainly respond with more aggressive rate cuts to stimulate activity and prevent a deeper contraction. The delicate balance between managing inflation and supporting employment defines the Fed’s dual mandate, making the assessment of these indicators paramount for future policy decisions.
Forecasting interest rates several years out is inherently fraught with uncertainty, given the multitude of domestic and international factors that can shift the economic landscape. Geopolitical tensions, technological advancements, shifts in global trade, and unexpected supply chain disruptions all carry the potential to alter the inflation and growth outlook, necessitating adjustments to monetary policy. This complexity contributes to the differing perspectives among Fed officials and independent analysts, with some advocating for a structurally higher neutral rate in a post-pandemic world, while others see a return to the lower rate environment that characterized much of the pre-COVID era.
For financial markets and businesses, the prospect of interest rates settling below 4.0% by 2027 would signal a return to a more accommodative monetary environment, potentially stimulating investment, easing borrowing costs for consumers, and boosting asset valuations. It would imply that the Fed has successfully navigated the inflation challenge without triggering a severe economic downturn. Conversely, if rates remain elevated above this threshold, it would suggest a more persistent battle with inflation or a higher structural cost of capital, potentially constraining growth and maintaining pressure on borrowers. The coming years will undoubtedly be characterized by intense scrutiny of incoming economic data, as the Federal Reserve navigates this intricate path, striving for price stability and maximum employment.
Stay Informed. Act Smarter.
Get weekly highlights, major headlines, and expert insights — then put your knowledge to work in our live prediction markets.
Related News
Fed Grapples With Long-Term Rate Outlook as 'Higher for Longer' Mantra Tested by Economic Data
Federal Reserve's Long-Term Strategy Under Scrutiny as Analysts Project Path to 2026 Rate Decisions
US Federal Reserve's Long-Term Interest Rate Path Under Intense Scrutiny
Federal Reserve's Rate Cut Prospects by 2026 Hinge on Evolving Inflation and Growth Data
Federal Reserve Prepares for Critical July 2026 Rate Decision Amid Evolving Economic Landscape
Fed’s Long-Term Inflation Fight Eyes 2.5 Percent Core PCE as Key Milestone
Federal Reserve's Long-Term Inflation Battle Intensifies Ahead of July 2026 Core PCE Report
Bank of England Navigates Complex Path Towards Potential Rate Cuts by Early 2027
Fed Signals Potential July Rate Cut as Inflation Cools and Growth Slows
Federal Reserve Eyes Steady Rates for September 2026 FOMC Meeting Amid Evolving Economic Data