
US Manufacturing Sector Grapples With Prolonged Contraction Ahead of Key PMI Report
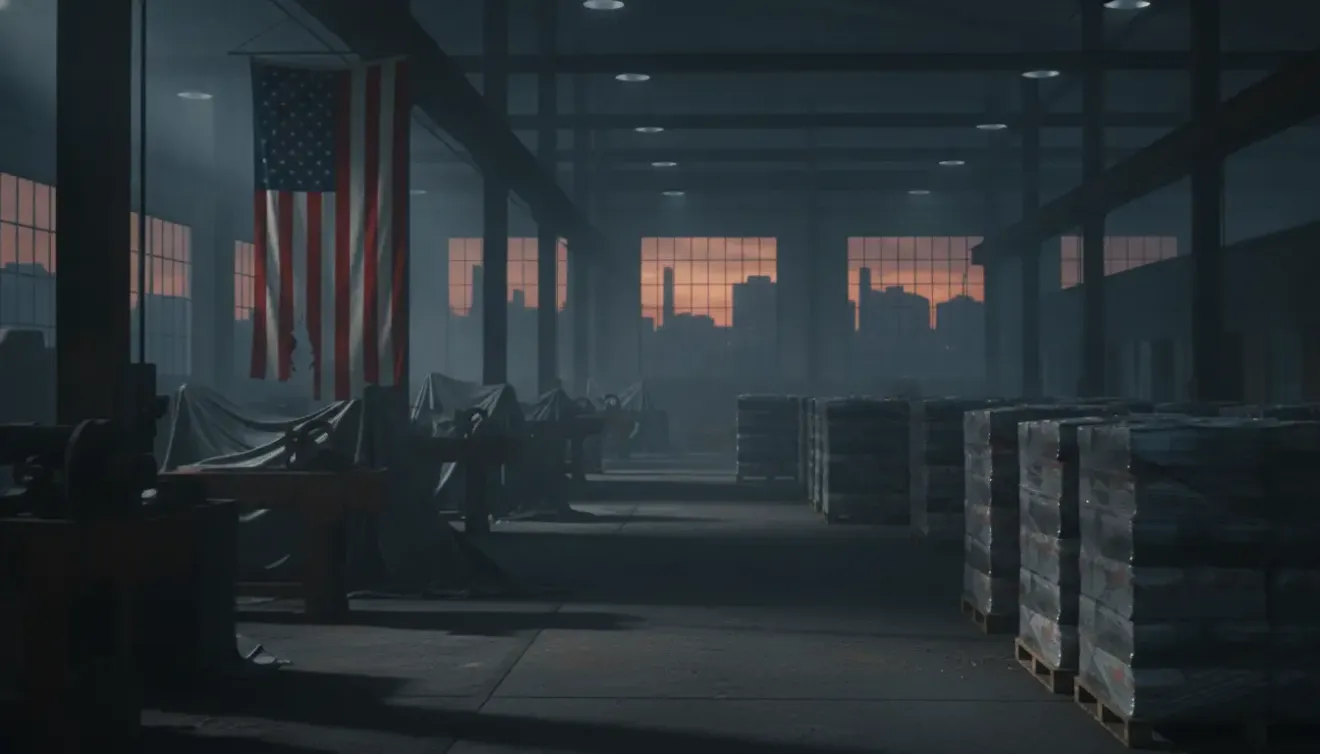
The United States manufacturing sector is bracing for another challenging report as the Institute for Supply Management (ISM) prepares to release its November 2026 Manufacturing PMI on December 1. Analysts and economists are closely watching the upcoming figures, with significant attention focused on whether the index will once again fall below the critical 50-point threshold, signaling continued contraction across the industrial landscape. A persistent trend of sub-50 readings would underscore a challenging environment for American factories, impacting investment decisions, employment, and the broader economic outlook.
The ISM Manufacturing PMI is a closely watched barometer of the nation's industrial health, derived from a survey of purchasing and supply executives across 18 manufacturing industries. It assesses new orders, production, employment, supplier deliveries, and inventories. A reading above 50 generally indicates expansion, while a figure below this benchmark suggests a contraction in manufacturing activity. The sector has been navigating headwinds ranging from fluctuating consumer demand to elevated interest rates, which have dampened capital expenditure and slowed inventory replenishment cycles. Global economic slowdowns and geopolitical uncertainties have also played a role, affecting export orders and supply chain stability.
The implications of sustained contraction extend beyond factory floors. A struggling manufacturing sector can ripple through the economy, potentially leading to job losses, reduced wage growth, and a dampening effect on consumer spending. Businesses may delay expansion plans, reduce hiring, and scale back production, contributing to a broader slowdown. Policy makers, particularly the Federal Reserve, will be scrutinizing the report for signs of how their monetary tightening efforts are impacting real economic activity, balancing the fight against inflation with the risk of tipping the economy into a deeper downturn.
Recent months have shown a mixed picture across various industrial sub-sectors. While some areas, particularly those tied to defense or essential goods, have demonstrated resilience, others, such as those sensitive to consumer discretionary spending or housing, have faced more pronounced declines. Supply chain issues, which were a significant concern during the pandemic, have largely eased, but inventory adjustments by businesses seeking to optimize stock levels have become a new headwind, sometimes leading to reduced orders for manufacturers. Energy costs, although volatile, continue to be a significant input for many industrial operations, adding pressure to profit margins.
Economists are divided on the exact trajectory, but many anticipate that conditions will remain tight through the end of the year. The Federal Reserve's stance on interest rates, while aimed at curbing inflation, inherently creates a more expensive borrowing environment for businesses, potentially stifling investment in new equipment and facilities. Furthermore, global demand remains somewhat subdued, limiting opportunities for export-driven growth. The November report will provide crucial data points for companies planning their strategies for the new year, offering a clearer picture of whether the manufacturing slump is deepening or showing early signs of stabilization.
The persistent challenge for the manufacturing sector highlights the delicate balance facing the US economy. While inflation has shown signs of moderation, the cost of achieving price stability has included a slowdown in key economic engines. Stakeholders across industry, finance, and government will be keenly awaiting the ISM data, recognizing its pivotal role in shaping perceptions and guiding decisions for the coming months. A sustained period below the 50-point mark would signal a entrenched contraction that could require further strategic adjustments from businesses and potentially influence future monetary policy considerations.
Looking ahead, the sector's recovery hinges on several factors: a sustained decline in inflation, leading to potential interest rate cuts; a rebound in global economic growth; and a renewed surge in consumer and business confidence. Until such catalysts emerge, the US manufacturing sector appears poised to navigate a period of continued caution and constraint, with the upcoming ISM report serving as a vital indicator of its immediate health.
Stay Informed. Act Smarter.
Get weekly highlights, major headlines, and expert insights — then put your knowledge to work in our live prediction markets.
Related News
US-Iran Tensions Escalate as Potential Military Options Against Nuclear Program Surface
US-Venezuela Talks Intensify Over Potential New Oil Drilling Rights for American Firms
Fears of Direct Conflict Mount as US and Iran Escalate Military Posturing in Persian Gulf
Bank of Japan Weighs Future Rate Hike Path Amid Inflationary Pressures, Yen Weakness
AI Logistics Firm NASN Intelligent Tech Sets August 7 Debut, Posing Key Test for Tepid IPO Market
Outpoll Weekly Recap: Finance (June 29 – July 5, 2026)
Rocket Lab Readies Neutron for Inaugural Launch Amid High Expectations
Shein Faces Intense Scrutiny After Public Debut with $26 Billion Valuation
Kendrick Lamar Album Speculation Reaches Fever Pitch Ahead of Possible December Release
Anticipation Builds for Taylor Swift's Next Global Tour Announcement